The FleetPartners takeover contest has entered a more serious phase, and the latest update confirms something the market already suspected: there is real strategic value in this business.
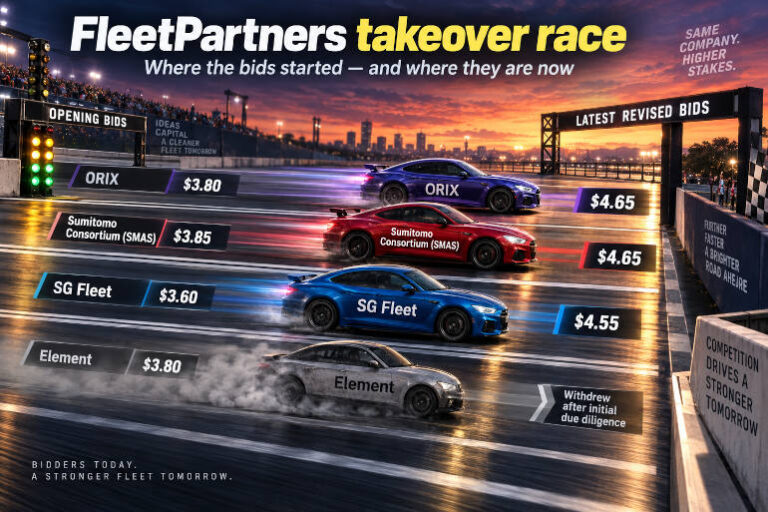
SG Fleet, ORIX and the Sumitomo Consortium have all returned with higher offers after getting access to FleetPartners’ books, while Element Fleet Management has decided not to submit a revised proposal.
The revised indicative offers now stand at $4.55 per share from SG Fleet and $4.65 per share from both ORIX and the Sumitomo Consortium. FleetPartners has decided to allow all three remaining parties into a further phase of due diligence.
That is a long way from where this process started.
Four suitors got a look under the bonnet
On 13 August, FleetPartners agreed to provide SG Fleet, Element and ORIX with initial limited commercial and financial due diligence access, subject to confidentiality agreements.
The stated purpose was to allow each bidder to decide whether it wanted to submit a revised proposal on a more informed basis.
Then another player slipped into the process.
On 25 August, a consortium comprising Sumitomo Corporation and Sumitomo Mitsui Auto Service Company Limited, or SMAS, submitted a $3.85 per share indicative proposal.
SMAS is the company behind Summit Fleet Leasing and Management, which makes its arrival particularly interesting for the Australian fleet market.
FleetPartners treated the Sumitomo Consortium consistently with the other bidders and granted it the same initial limited commercial and financial due diligence access.
So at one point, four major fleet management interests had been invited into the data room.
That is an unusual position for any fleet management business to find itself in.
Everyone has now seen more than the brochure
There is an interesting competitive consequence to all of this.
SG Fleet, Element, ORIX and the Sumitomo Consortium have all had access to limited commercial and financial due diligence information about FleetPartners.
Put less politely, most of the major players in the market have now had a look up the skirt.
They may not have seen everything, and the access has been described as limited, but they have seen enough to make more informed decisions about what FleetPartners is worth and how the business operates.
That raises a fascinating question if some of these parties ultimately walk away.
They will still have learned more about FleetPartners’ economics, customer mix, cost structure, funding model and operating performance than they knew before the process began.
Assuming the confidentiality agreements do their job, that information cannot simply be used elsewhere. But strategically, the bidders have now had a much closer look at the recipe for FleetPartners’ secret sauce — if there is one.
That makes this process more than an auction for shareholders. It is also a rare moment where several major competitors have been able to assess the same fleet management platform from the inside.
Element walks away
Element’s withdrawal is notable because it had positioned itself as a serious strategic buyer.
It had previously offered $3.80 per share and argued that FleetPartners represented “a rare opportunity to add meaningful capability in a market we know exceptionally well”.
Element also described itself as having significant financial capacity and said the proposed acquisition would preserve the strength and flexibility of its balance sheet.
But after completing the initial due diligence process, Element informed FleetPartners that it would not submit a revised proposal.
That decision is important because Element is a global fleet management pure play with more than 1.5 million vehicles under management globally and an established Australian and New Zealand business through Custom Fleet.
If Element has decided the numbers no longer stack up at the higher end of the bidding range, the remaining bidders will have reached a different conclusion.
SG Fleet is still fighting
SG Fleet is still very much in the race.
Its revised offer of $4.55 per share is below the $4.65 currently proposed by ORIX and the Sumitomo Consortium, but price is not the only consideration in a transaction like this.
The FleetPartners Board has made clear that the revised proposals have different terms and conditions, and that further due diligence requests also vary between bidders.
SG Fleet also has the strongest immediate scale argument.
A successful acquisition would add FleetPartners’ more than 80,000 vehicles under management to SG Fleet’s already substantial Australia and New Zealand portfolio.
It would also remove a major competitor.
That strategic value may explain why SG Fleet has continued to increase its offer through the process.
ORIX and Sumitomo now lead on price
ORIX and the Sumitomo Consortium are currently level at $4.65 per share.
Both bring significant fleet management experience and broader Asia-Pacific capability.
The Sumitomo Consortium’s arrival is particularly interesting because SMAS already has exposure to the Australian fleet management sector through Summit Fleet Leasing and Management.
That means the contest is no longer simply about an incumbent giant defending its position or an overseas player trying to enter the market.
It is now a competition between fleet management groups that already understand the sector and can see the benefits of adding FleetPartners’ customers, systems, people and vehicle portfolio.
What happens next?
FleetPartners has now granted SG Fleet, ORIX and the Sumitomo Consortium access to a further phase of due diligence.
That is the most important next step.
The three remaining parties can now undertake a deeper examination of the business before deciding whether to move from indicative proposals to binding offers.
FleetPartners has not said how long this next stage will take, and there is still no certainty that any of the revised proposals will result in a binding transaction.
The Board will continue assessing not just the headline price, but the terms and conditions attached to each offer.
For shareholders, the competition has already done its job. The original SG Fleet offer was $3.60 per share. The leading indicative offers are now $4.65.
For the fleet industry, though, there may be a second story unfolding. By the time this process ends, almost every major player that could realistically buy FleetPartners will have had a close look at the business.
One of them may eventually own the secret sauce. The others will at least know what ingredients went into it.